August 30, 2026 · G20 / trade diplomacy / Treasury
Bessent heads into Asheville G20 meeting pushing trade-imbalance, Iran and growth agenda
DOCUMENTED POLICY AGENDA / OUTCOME NOT YET DETERMINED — NOT THERMOMETER-RATED
Not rated on the thermometerThis item records a legal/policy position or unresolved institutional dispute rather than a single rateable factual proposition.
What is being said
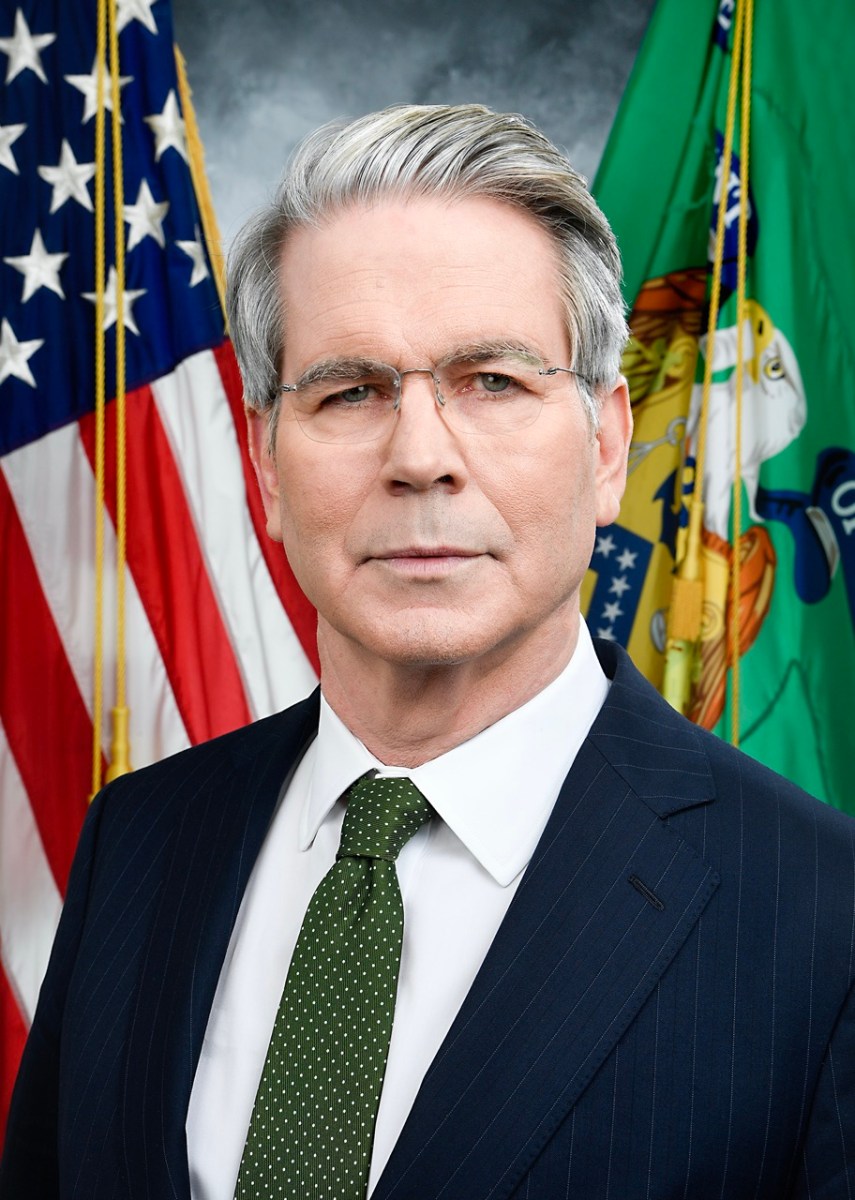
Reuters reported that Treasury Secretary Scott Bessent is using the upcoming G20 finance ministers and central bank governors meeting in Asheville, North Carolina, to press U.S. positions on trade imbalances, growth, business ties with Iran, deregulation and energy expansion.
What the record shows
Reuters’ August 30 preview describes stated U.S. negotiating priorities ahead of the Asheville meeting. It also reports substantial disagreement among G20 members over tariffs, Chinese industrial overcapacity, debt and geopolitical issues. Because this is a description of an announced diplomatic agenda before the meeting’s outcome is known, FactFlag records the objectives and the areas of dispute without treating them as achieved results.
Response / rebuttal
The item is useful as a current record of Bessent’s stated economic-diplomacy priorities. Any later claim that the meeting produced specific concessions or agreements should be checked against the final communiqué, Treasury releases and participating governments’ records.
Limits / uncertainty: This entry does not predict G20 outcomes or assess whether the administration’s tariff, sanctions, debt-management or growth policies will achieve their stated goals.
August 30 follow-up: FactFlag’s existing update feed records AP reporting that Bessent said Treasury planned another Iran-related bank sanction; the target bank remained unidentified pending an official designation.
August 24, 2026 · scope checked August 25 · Iran sanctions / Treasury / Secondary sanctions
Bessent formally launches “Operation Economic Outcast” against Iran and its enablers
DOCUMENTED TREASURY ACTION / SCOPE NEEDS CONTEXT — NOT THERMOMETER-RATED
Not rated on the thermometerThis item records a legal/policy position or unresolved institutional dispute rather than a single rateable factual proposition.
What is being said
Treasury Secretary Scott Bessent announced Operation Economic Outcast as a new whole-of-government economic campaign against Iran, warning that foreign actors maintaining specified economic ties can face U.S. sanctions exposure.
What the record shows
Treasury’s August 24 primary release formally launches Operation Economic Outcast at Trump’s direction. The White House uses the same official name. Reuters reported roughly 60 new sanctions targets and broader secondary-sanctions exposure across sectors including digital assets, gold, aviation, technology and shipping. The public record reviewed for this entry does not show blanket sanctions already imposed on every country, bank or company that continues Iran-related business, so the implemented designations and risk warnings remain separate from threatened future penalties.
Response / rebuttal
Bessent described the campaign as an economic onslaught intended to sever Iran’s financial connections. That objective and the administration’s historical superlatives are policy framing; the concrete record is the operation’s launch, new designations and expanded sanctions-risk categories.
Limits / uncertainty: Secondary-sanctions exposure is not identical to an automatically imposed penalty. Designations, licenses, exemptions and enforcement actions are legally distinct and can change over time.
August 20, 2026 · implementation clarified August 24 · Treasury debt management / bond-market intervention
Bessent says Treasury may expand bond buybacks further as federal debt passes $40 trillion
DOCUMENTED TREASURY ACTION / FORWARD-LOOKING FISCAL CLAIM — NOT THERMOMETER-RATED
Not rated on the thermometerThis item records a legal/policy position or unresolved institutional dispute rather than a single rateable factual proposition.
What is being said
Bessent said Treasury may expand long-dated bond buybacks and later confirmed that the department would continue its regular auction schedule while carrying out the larger liquidity-support operations. He has described the intervention as a market-liquidity tool rather than a replacement for normal Treasury financing.
What the record shows
Treasury’s August 19 primary announcement doubled the maximum size of selected 10-to-20-year and 20-to-30-year liquidity-support buybacks from $2 billion to at least $4 billion per operation for the remainder of the refunding quarter. Reuters reported August 24 that Bessent said regular Treasury auctions would continue and that no bonds had yet been purchased under the enlarged program. The public record therefore supports an announced and scheduled expansion, but not a claim that the larger repurchases had already been executed. Trump’s August 21 statement that Bessent initiated the tactical intervention himself remains an attributed presidential account rather than an independently reconstructed internal decision log.
Response / rebuttal
Bessent has characterized the enlarged buybacks as targeted liquidity support in thinner long-dated markets while keeping Treasury’s ordinary auction financing in place. Trump has separately said the specific market intervention was Bessent’s decision, while Bessent has described a broader Trump-directed fiscal-consolidation effort with OMB Director Russ Vought.
Limits / uncertainty: As of Bessent’s August 24 remarks, the enlarged buyback program had been announced and scheduled but the larger purchases had not yet occurred. Treasury buybacks can improve market liquidity but do not by themselves eliminate deficits or reduce gross debt in the same way as debt retirement funded by sustained budget surpluses.
Directly related evidence records
These records are stored once in the canonical evidence archive and surfaced here because this person is directly involved in the underlying action, agency, statement or dispute.
August 26, 2026 · Counterterrorism sanctions / Palestine Action / far-left extremism policy · Directly related record
Treasury sanctions Palestine Action under U.S. counterterrorism authority as administration broadens focus on violent far-left networks
DOCUMENTED TREASURY COUNTERTERRORISM SANCTIONS — PALESTINE ACTION ADDED TO OFAC SDN LIST UNDER E.O. 13224; TREASURY'S UNDERLYING TERRORISM CHARACTERIZATION IS AN EXECUTIVE-BRANCH DETERMINATION, NOT A COURT CONVICTION
Not rated on the thermometerThis related item is a policy/public-record development rather than a single rateable factual proposition.
Why it appears on this profile: Treasury Secretary Scott Bessent announced the sanctions and framed them as part of the administration’s broader counterterrorism strategy. This cross-profile link records his department’s action and public explanation, not a personal criminal-law finding.
What is being said
Treasury described Palestine Action, Autistici Inventati and Masar Badil as part of a broader violent far-left terrorism threat and said U.S. financial tools would be used against such groups and their enablers. Reuters reported the action as part of the Trump administration’s counterterrorism push against far-left organizations.
What the record shows
Treasury’s August 26 release says OFAC designated Palestine Action pursuant to Executive Order 13224, as amended, for materially assisting, sponsoring or providing financial, material or technological support for, or goods or services to or in support of, an act of terrorism. OFAC’s same-day recent-actions page records counterterrorism designations and SDN-list updates. Treasury also noted that the UK had proscribed Palestine Action under its Terrorism Act in July 2025. The U.S. action is a Treasury sanctions designation under executive counterterrorism authority; it is not the same legal instrument as a State Department Foreign Terrorist Organization designation, and FactFlag does not describe it as a U.S. criminal conviction.
Assessment context: The OFAC action is directly documented in primary Treasury records and independently reported by Reuters. Because the legal status and financial consequences are concrete, the sanctions action is documented. But the administration’s broader political characterization of “far-left terrorism” and the factual basis for each underlying allegation remain analytically separate from the existence of the sanctions designation itself.
Open canonical evidence record →
August 21, 2026 · Federal debt / Economic growth / Fiscal policy · Directly related record
Trump says economic growth will solve the $40 trillion federal-debt problem “with great ease”
ECONOMIC FORECAST — UNRATED / CURRENT BASELINE DOES NOT SHOW DEBT STABILIZING
Not rated on the thermometerThis related item is a policy/public-record development rather than a single rateable factual proposition.
Why it appears on this profile: As Treasury Secretary, Bessent manages federal borrowing and the Treasury market and has publicly described the administration’s growth-and-fiscal-consolidation strategy; this relation records direct institutional responsibility for debt management, not authorship of Trump’s statement.
What is being said
Speaking to reporters before traveling to South Carolina on August 21, Trump said the country was experiencing “tremendous” growth and that growth would solve the federal-debt problem “with great ease.” He described growth as the way to manage the debt.
What the record shows
The debt milestone itself is documented: Reuters reported that gross federal debt had crossed $40 trillion, more than double its 2017 level. Economic growth can reduce a debt burden relative to the size of the economy when nominal GDP grows faster than debt. But current official data do not establish that this is already happening. BEA’s advance estimate put real GDP growth at a 1.5% annual rate in the second quarter of 2026, down from 2.1% in the first quarter. CBO’s February 2026 baseline projects a $1.9 trillion federal deficit in 2026, rising to $3.1 trillion in 2036, and projects debt held by the public rising from about 101% of GDP in 2026 to 120% in 2036. CBO says the 2025 reconciliation law increased projected 2026–2035 deficits by roughly $1.4 trillion relative to its January 2025 baseline, partly offset by higher tariff revenue. Those projections can change with legislation, growth, inflation, interest rates and other developments, but they do not presently support describing debt stabilization as an already demonstrated result.
Assessment context: This is principally a forward-looking economic judgment, so FactFlag does not assign a numerical FactFlag Meter score. Faster growth can materially improve fiscal sustainability, and the administration is entitled to pursue a growth-led strategy. The evidence check is narrower: Trump’s confident “with great ease” prediction is not established by current official projections, which still show debt rising faster than the economy under current law.
Open canonical evidence record →
August 19, 2026 · Operation Economic Outcast launched August 24; scope checked August 25 · Iran / Economic sanctions / Secondary pressure · Directly related record
Trump’s Iran economic-pressure campaign becomes “Operation Economic Outcast,” with dozens of new sanctions targets and broader secondary-sanctions risk
POLICY CAMPAIGN — NEW IRAN DESIGNATIONS ANNOUNCED / BROADER SECONDARY-SANCTIONS WARNING; NO THIRD-COUNTRY PENALTIES ANNOUNCED YET
Not rated on the thermometerThis related item is a policy/public-record development rather than a single rateable factual proposition.
Why it appears on this profile: Treasury Secretary Scott Bessent is directly involved because Treasury has been implementing the Economic Fury sanctions campaign and had publicly signaled additional Iran economic measures before Trump’s August 19 escalation announcement.
What is being said
In a Truth Social post reported late August 19, Trump said he was announcing the “most crushing economic operation ever taken against any country,” described it as economic warfare and isolation on an unprecedented scale, and warned third countries that economic support for Iran could bring severe consequences. He specifically referenced oil smuggling, swap lines, cash transfers, exchange houses, ship registries and front companies.
What the record shows
Treasury’s August 24 primary release formally names the campaign “Operation Economic Outcast” and says it began at President Trump’s direction. The White House separately published a same-day release using that name and describing a whole-of-government effort to isolate Iran economically. Independent Reuters reporting says the package covered roughly 60 individuals, entities and vessels and widened secondary-sanctions exposure across sectors including digital assets, gold, aviation, technology and shipping. The public record reviewed for this update still does not show blanket penalties already imposed on every third-country government, bank or company that maintains Iran-related commerce. FactFlag therefore distinguishes the formal launch and listed sanctions from threatened future secondary sanctions and from the administration’s political descriptions of the campaign as unprecedented or the “single greatest” financial offensive ever mounted.
Assessment context: The August 24 primary records resolve the campaign’s official name and implementation stage: Operation Economic Outcast is no longer merely a threatened or unnamed escalation. The supportable facts are the formal launch, newly designated targets and expanded sanctions-risk categories. Claims that it is the toughest, greatest or most crushing economic campaign in history remain non-quantified political characterizations and are not treated as independently proven.
Open canonical evidence record →
August 19, 2026 · implementation timing clarified August 24 · Federal debt / Treasury markets / Fiscal policy · Directly related record
U.S. debt crosses $40 trillion as Treasury expands long-bond buybacks and Trump directs fiscal-consolidation effort
PUBLIC FISCAL RECORD — BUYBACK ACTION DOCUMENTED; TRUMP’S DIRECTION CLAIM IS ATTRIBUTED, NOT INDEPENDENTLY VERIFIED
Not rated on the thermometerThis related item is a policy/public-record development rather than a single rateable factual proposition.
Why it appears on this profile: As Treasury secretary, Bessent leads the department that announced the larger long-duration buyback operations and manages federal debt issuance and market-liquidity policy.
What is being said
Treasury announced that maximum liquidity-support buybacks in the 10-to-20-year and 20-to-30-year nominal sectors would rise from $2 billion to at least $4 billion per operation. Bessent later said normal Treasury auctions, including long-dated debt sales, would continue. On August 21 Trump said he had not instructed Bessent to make the bond-market intervention and that the Treasury secretary acted on his own authority.
What the record shows
Treasury’s August 19 primary release says the larger long-end liquidity-support buyback sizes become effective in September 2026 and remain in effect through the refunding quarter, while the department’s quarterly-refunding page continues to publish the regular auction and buyback schedules. Reuters reported August 24 that Bessent said Treasury would continue the regular auction program despite the larger buybacks; Reuters also reported that Treasury had not yet purchased bonds under the enlarged program and that the first enlarged 10-to-20-year operation was still prospective. That matters because an announced expansion is not the same thing as completed repurchases. The public record still does not independently resolve who first proposed or approved the tactical size increase. Buybacks are debt-management/liquidity operations and do not, by themselves, reduce enacted deficits or net federal indebtedness.
Assessment context: The August 24 update clarifies implementation status rather than changing the underlying policy: Treasury formally increased future long-end buyback capacity, but the enlarged operations had not yet executed when Bessent spoke. FactFlag therefore separates authorization/scheduling, actual repurchases, and the separate political question of who initiated the intervention.
Open canonical evidence record →
July 17, 2026 · Immigration / Banking access / White House policy · Directly related record
Stephen Miller says Trump ordered banks to stop serving undocumented immigrants
OVERSTATED — THE ORDER DOES NOT CATEGORICALLY BAN BANK ACCOUNTS
 78% evidence gapWELL SUPPORTED
NOT SUPPORTEDWhy it appears on this profile: The executive order assigns implementation work to the Treasury Department, and Treasury/FinCEN issued the June advisory that Miller cited as the next stage of the policy.
What is being said
During a July 17 interview on The Clay Travis and Buck Sexton Show, White House Deputy Chief of Staff Stephen Miller said Trump had signed an executive order “saying that we are not going to allow illegal aliens to use banking services in this country.” He added that shutting down access to credit cards, bank accounts and direct deposit would be “a massive engine for deportation.”
What the record shows
Executive Order 14406, signed May 19, directs Treasury and federal financial regulators to flag suspicious activity tied to unlawful employment, consider stronger customer-due-diligence rules, allow additional immigration-status information when relevant to fraud or other illicit-finance risks, and consider credit risks tied to loss of lawful work authorization. It does not order banks to close every account held by an undocumented person or categorically bar such people from ordinary deposit accounts. The CFPB’s current consumer guidance also states that a Social Security number is not required to obtain a bank or credit-union account, while existing credit rules permit creditors to consider immigration status in evaluating repayment risk. Treasury’s June 5 FinCEN advisory likewise focuses on suspicious activity and unlawful-employment schemes rather than a universal account ban.
Assessment context: Miller accurately described an administration effort to use financial regulation as part of immigration enforcement, but he overstated what the signed executive order itself says. The order creates a risk-based regulatory and enforcement framework; it does not enact the categorical nationwide banking-services prohibition his wording suggests.
Open canonical evidence record →